Licensed Health Insurance Agent · 19 States
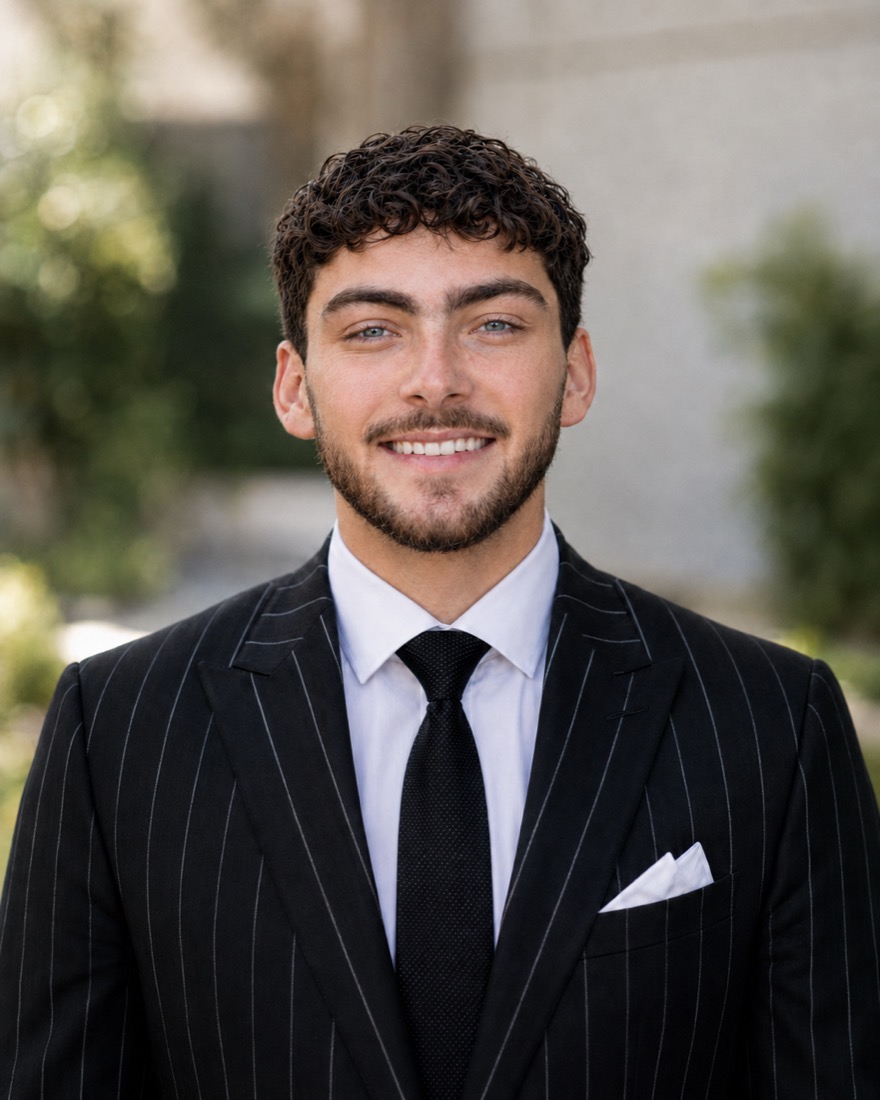
I'm Josh Cutlan. I help individuals, families, and the self-employed compare private and Marketplace plans and pick the one that fits. Free to work with, no pressure, and I answer my phone.
Who you're working with
I'm originally from Illinois and now call Florida home, where I live with my family. I got into health insurance through my brother, who's been in the industry for years — and it clicked fast. I saw firsthand how much the right guidance matters when someone's staring down a wall of confusing plans, prices, and fine print.
"My job isn't to sell you the biggest plan — it's to find the one that actually fits your life."
That's the part I love: taking something stressful and making it simple, so you can make a confident choice and get back to your life. When I'm not helping clients, I'm a die-hard hockey fan and I travel every chance I get.
Most people only look closely at their health plan when something goes wrong, and by then there are fewer choices. I run Cutlan Health Solutions as part of Fuller Built Insurance, so you get one-on-one service with a proven team behind me.
Your situation
Tap the closest match. Each one opens a guide or a quick form.
COBRA paperwork on the way? You have 60 days to compare before you decide.
Read the guide →Find out the exact day a parent's plan ends, and line up the next one.
Read the guide →Does your paycheck deduction feel high for what you get? Check it against a plan priced for you.
Read the guide →Freelancing, contracting, or running your own business with no employer plan.
Read the guide →A spouse, kids, or both, on one plan or split across two.
Start a quick form →Coverage for you, or for you and a few employees.
Start a quick form →Working with me
Book a call, text me, or fill out the quick form. I ask about your doctors, your budget, and how you use care.
Private and Marketplace options next to each other, with what each one costs you in a quiet year and a rough one.
I do the enrollment paperwork with you, and I'm still your agent at renewal time.
What I compare
I look at private plans and Marketplace plans for you, then lay them out next to each other so the tradeoffs are plain.
Medically-underwritten plans with broad, nationwide networks. They ask health questions and can say no, but they're often a great fit for healthy individuals and families.
Help comparing Healthcare.gov / Marketplace plans and checking whether you qualify for income-based subsidies.
Coverage built for freelancers, contractors, and small business owners.
Plans that protect your people without blowing up your monthly budget.
Lost employer coverage? I'll help you find a plan that often costs less than COBRA.
Bridge coverage for anyone not yet eligible for Medicare.
What you can count on
The person you talk to on day one is the person who answers your texts a year later.
If your work plan or a Marketplace plan is the better deal, I'll tell you and point you there.
I check plans from several carriers, so you aren't stuck with one company's lineup.
Claims questions, a new baby, a move, a raise: text me and we'll sort out what changes.
Coverage area
Based in the Tampa, FL area and licensed to help clients in these states.
My license in these states is on the way. Until then, I can connect you with a licensed agent I trust.
I'm not licensed in these, so I can't enroll you myself. Text me and I'll connect you with a licensed agent I trust.
Read first
Plain-English answers to the questions clients bring me most.
Plan letters
The letters tell you who you can see and whether you need a referral first. Many of the self-employed people and families I help lean toward PPO-style plans so they can pick their own doctors.
| Plan type | Flexibility | Referrals | Network | Typical cost |
|---|---|---|---|---|
| PPO | Highest — see who you want | Not required | Broad, often nationwide | Higher premium, more freedom |
| HMO | Lowest — stay in-network | Required (via PCP) | Narrow, local | Lowest premium |
| EPO | Middle ground | Not required | Moderate | Lower-to-mid premium |
| POS | Hybrid | Required (via PCP) | Some out-of-network | Mid premium |
Not sure which fits? That's what I'm for — tell me how you use healthcare and I'll match you to the right structure.
FAQ
If yours isn't here, text me and I'll answer it.
Nothing. It's free to work with me — insurance carriers build the agent's compensation into the plan whether or not you use one, so you pay the same premium either way. You just get someone comparing your options and answering your calls.
Carriers build agent pay into the plan's price whether or not you use an agent, so the same plan costs the same from the carrier, on the Marketplace, or through me. What you get through me is the comparison, and someone who picks up when you have a question later. More on how I'm paid.
Absolutely — that's who I help most. Self-employed people, 1099 contractors, and freelancers have two main paths: ACA Marketplace plans (guaranteed acceptance, possible income-based subsidies) and private PPO plans (they ask health questions and can say no, but are often lower cost with broader networks for healthy applicants). I'll compare both for your situation.
Maybe. At most jobs, everyone on the same plan pays the same paycheck deduction whether they're 24 or 60, and adding a spouse often costs a lot more. A private plan priced on your age and health can cost less for some young, healthy people. You'd give up your employer's share and the pre-tax deduction, and private plans can decline applicants or exclude pre-existing conditions, so I compare the real numbers before you change anything.
ACA Marketplace plans accept everyone, cover pre-existing conditions, and offer income-based subsidies, but are often HMOs limited to open enrollment. Private PPO plans are medically underwritten — you can be declined — but for healthy applicants they often cost less, offer broad nationwide networks, and can be bought year-round.
ACA Marketplace plans generally require open enrollment (about Nov 1 to mid-January) unless you have a qualifying life event like losing coverage. Private medically-underwritten plans can be applied for year-round; they ask health questions and can decline you.
19 states: Colorado, Florida, Georgia, Illinois, Indiana, Kansas, Kentucky, Maryland, Michigan, Missouri, North Carolina, Ohio, Oklahoma, South Carolina, Tennessee, Texas, Utah, Virginia, and Wisconsin. Coming soon: Nevada, Iowa, and Montana; until then I can connect you with a licensed agent I trust. In Alabama, Arkansas, Delaware, Louisiana, Mississippi, Nebraska, South Dakota, West Virginia, and Wyoming, I can connect you with a licensed agent too. Based in the Tampa, FL area.
No. My job is to find the right fit, not the biggest sale. If a Marketplace plan is your better deal, I'll tell you. No pressure, no spam calls.
No. This is my own site. I'm an independent licensed insurance agent, and I'm not HealthCare.gov or affiliated with or endorsed by any government agency.
Start a free quote on this site, or call or text (813) 601-6884. I usually respond the same day.
Look me up
You shouldn't have to take my word for it. These links show my license and number.
Independent insurance agent — not affiliated with or endorsed by any government agency or Healthcare.gov.
Reviews
Client feedback means everything to me. If we've worked together, I'd be grateful for a quick Google review — and if you're checking me out, see what others have to say.
Free · No pressure · 60 seconds
Grab 15 minutes on my calendar, or answer a few quick questions and I'll put together your real options, usually the same day.